Ammonium Bicarbonate (E503(ii)) CAS: 1066-33-7
Ammonium Bicarbonate (E503(ii)) CAS: 1066-33-7
This week's agrochemical intelligence highlights fertilizer supply recovery, phosphate pricing, urea market developments, Bangladesh's ammonia restart, and upcoming EU trade decisions that could reshape procurement strategies during Q3 2026.
The gradual restart of Gulf sulfur exports is expected to improve global sulfur availability and ease sulfuric acid market tightness. Fertilizer, mining, and battery manufacturers should prepare for improving supply conditions during Q3 2026.
Qatar sits at the crossroads of geopolitical uncertainty and commercial strain as US‑Iran talks stall and LNG disruptions persist. Chemical buyers now question whether QatarEnergy can honour investment plans and restore export flows while QAFCO navigates force majeure timelines. The outcome will reshape ammonia, urea, and fertilizer pricing across Asia.
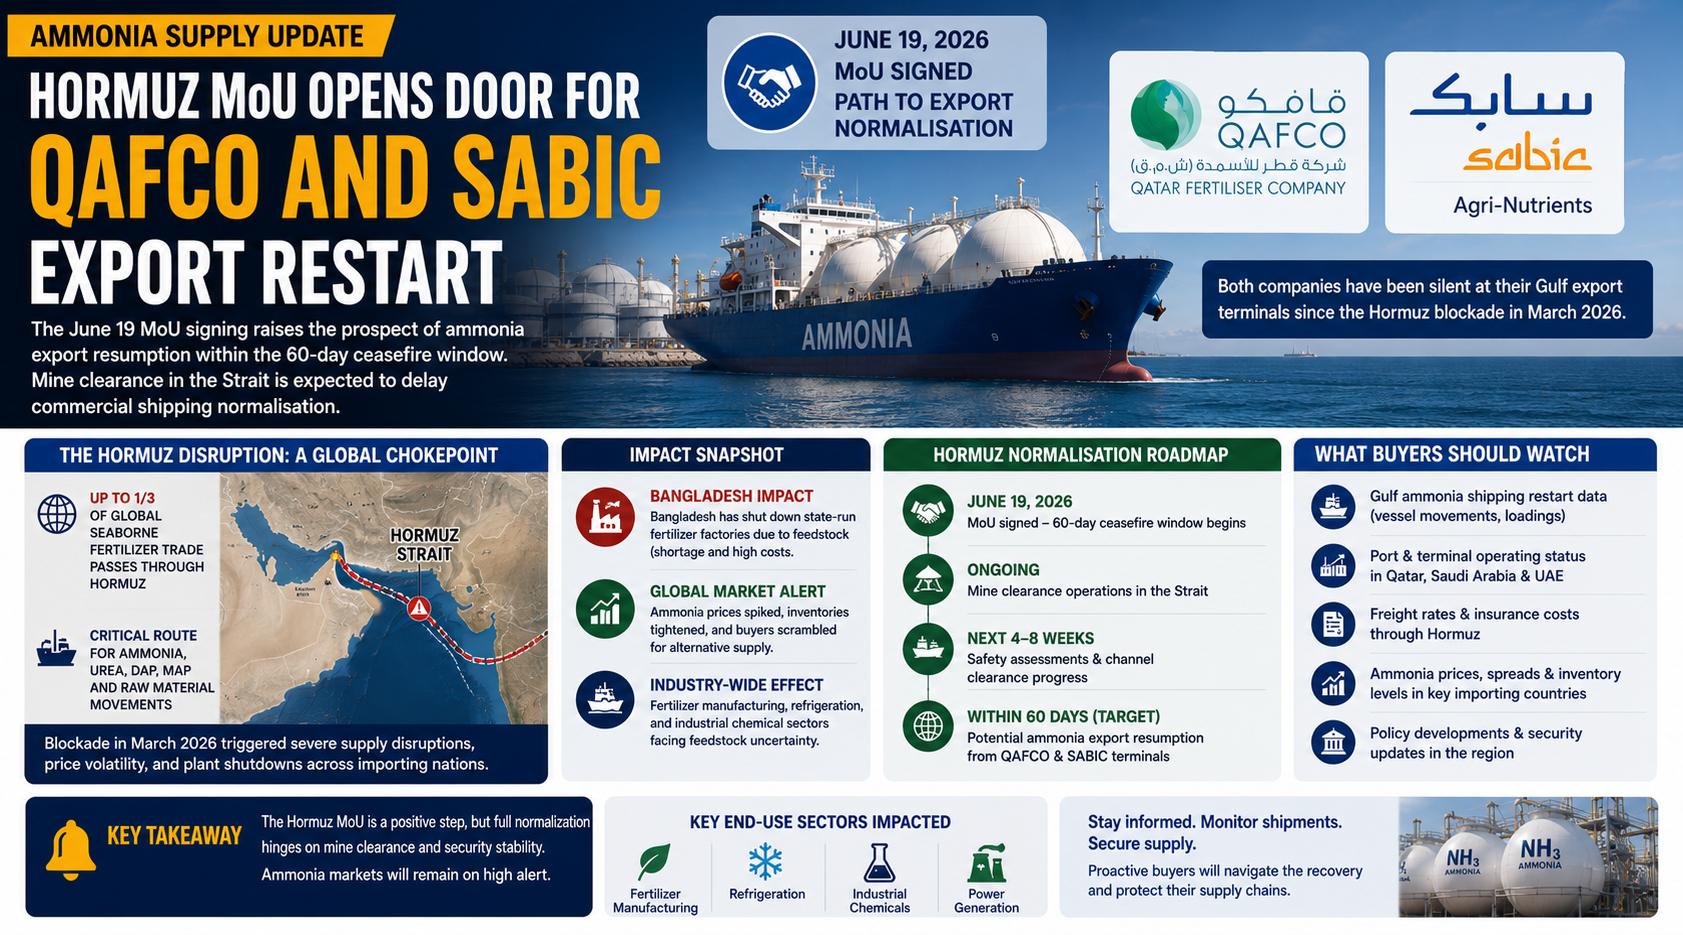
The Bürgenstock roadmap and recent Hormuz transit data signal a clear path for QAFCO and SABIC to resume ammonia exports in Q3 2026. While force majeure conditions may lift in July, mine clearance delays could postpone full tanker capacity until August. Agricultural and industrial buyers should prepare for an improved but staggered supply outlook.
Sulfuric acid buyers face continued supply planning challenges as Hormuz recovery progresses but shipping restrictions remain. This analysis explains the impact on fertilizer, mining and industrial users through Q3 2026.
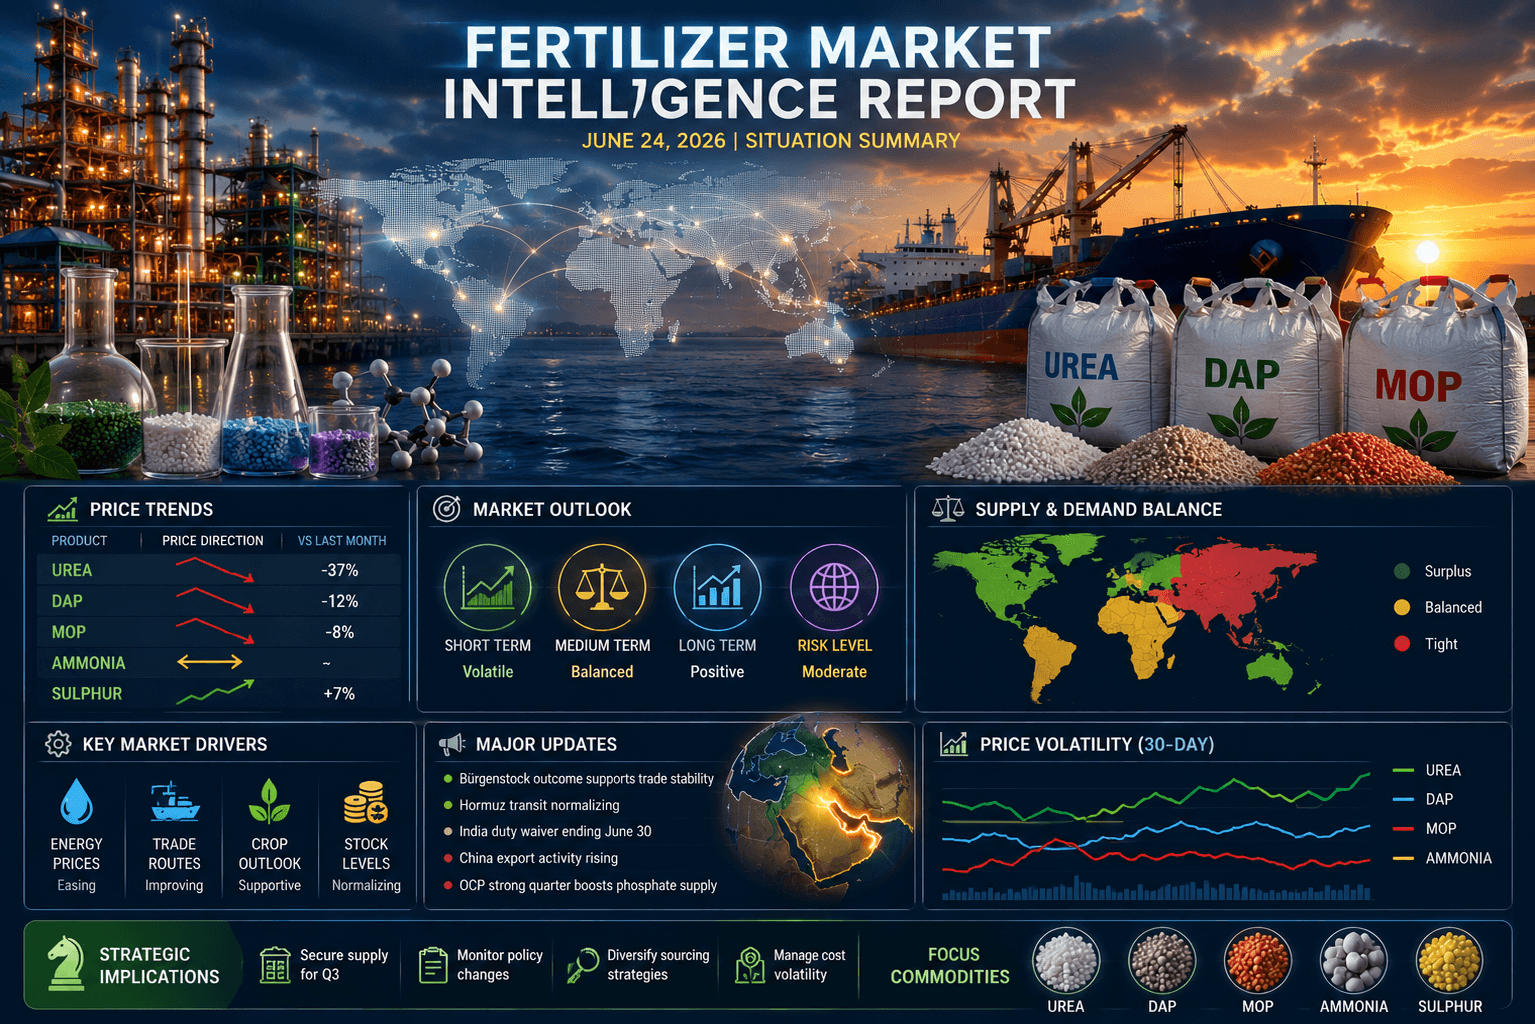
Global fertilizer markets are stabilizing after months of disruption, but June 2026 remains a critical procurement window. Urea prices are down 36%, ammonia exports may restart in July, and fertilizer buyers must navigate supply recovery, policy deadlines, and pricing uncertainty.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.