Citrus Pulp CAS: 94266-47-4
Citrus Pulp CAS: 94266-47-4
The recent persistence of DAP price strength underscores a tightening phosphate supply chain, heightened global fertilizer demand, and growing procurement risks for agriculture stakeholders. As phosphate trade remains constrained, buyers must reassess sourcing strategies amid volatile market conditions.
Australia enters its critical pre-season agricultural procurement period with improving global logistics, lower freight costs and stronger chemical supply conditions. For fertilizer and agrochemical buyers, July represents the most important purchasing month before spring planting begins.

In early 2026 the global chemical market saw a dramatic price spike during the Hormuz crisis, only to reverse course by April even before shipping lanes fully reopened. This article dissects the panic‑driven surge, the factors that triggered the drop, and the procurement intelligence lessons that can help buyers mitigate volatility.

Ammonia availability in Q3 2026 is rebounding, shifting power back to sellers. Indian buyers, once dominant in phosphoric acid pricing, now face tighter margins and less bargaining room. Learn how supply dynamics reshape fertilizer procurement strategies.
The UN warns 9.1 million more people in Asia could face acute food insecurity if fertilizer supply disruptions continue through July. For agricultural procurement teams, ammonia and urea supply recovery is now an operational priority with direct consequences for global crop production.
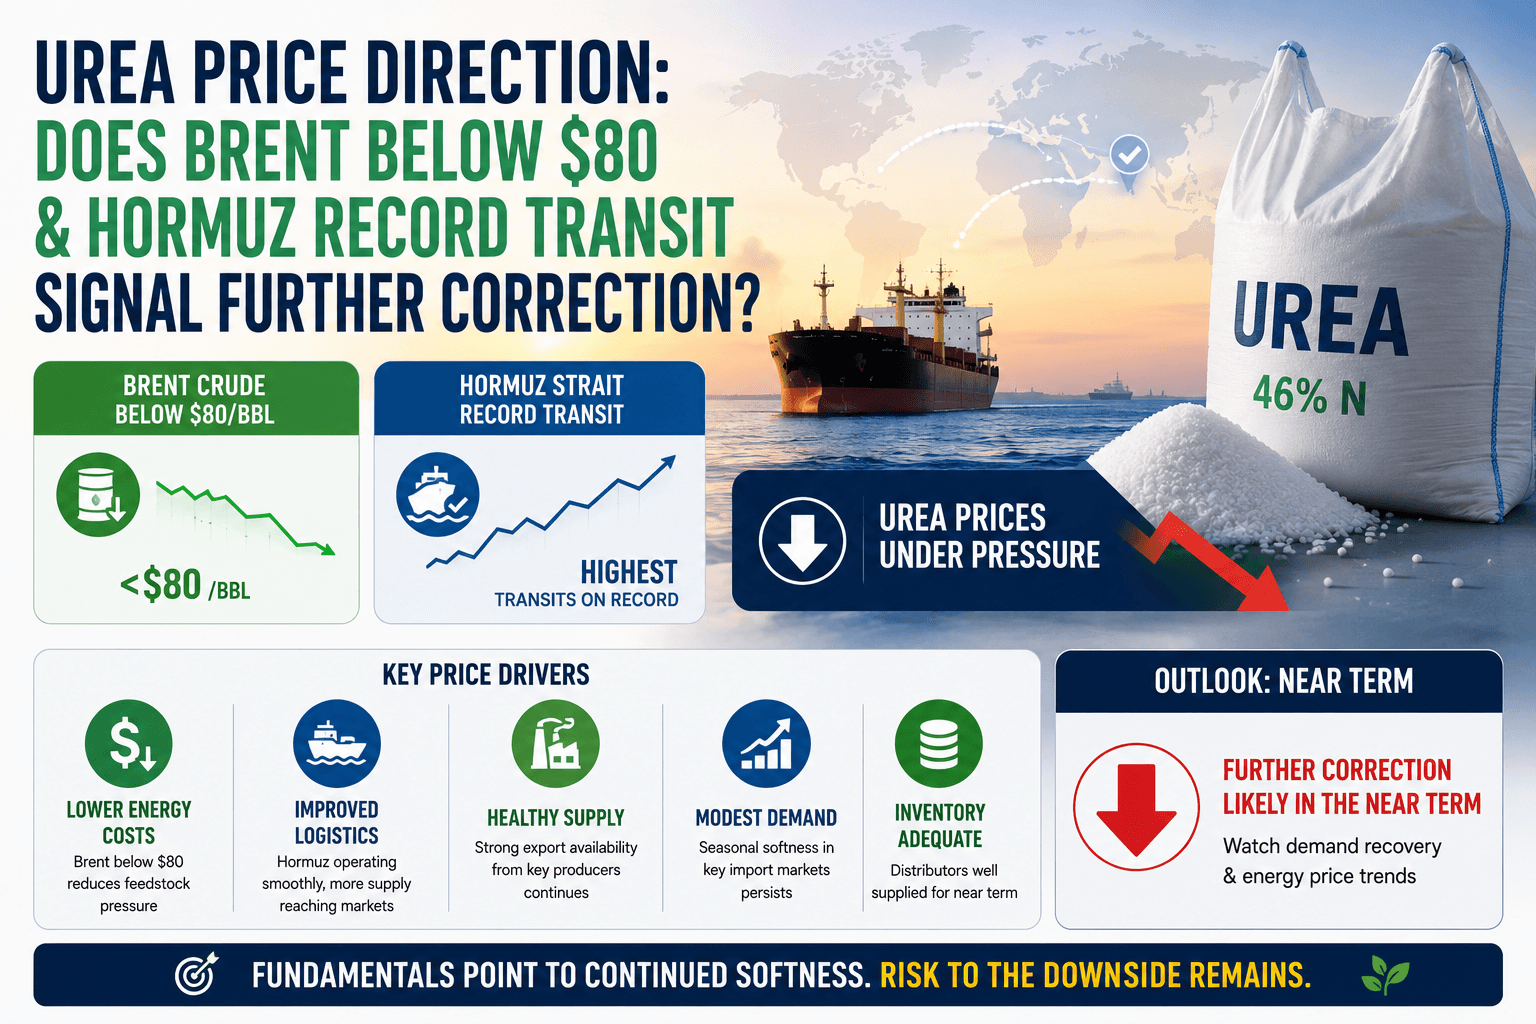
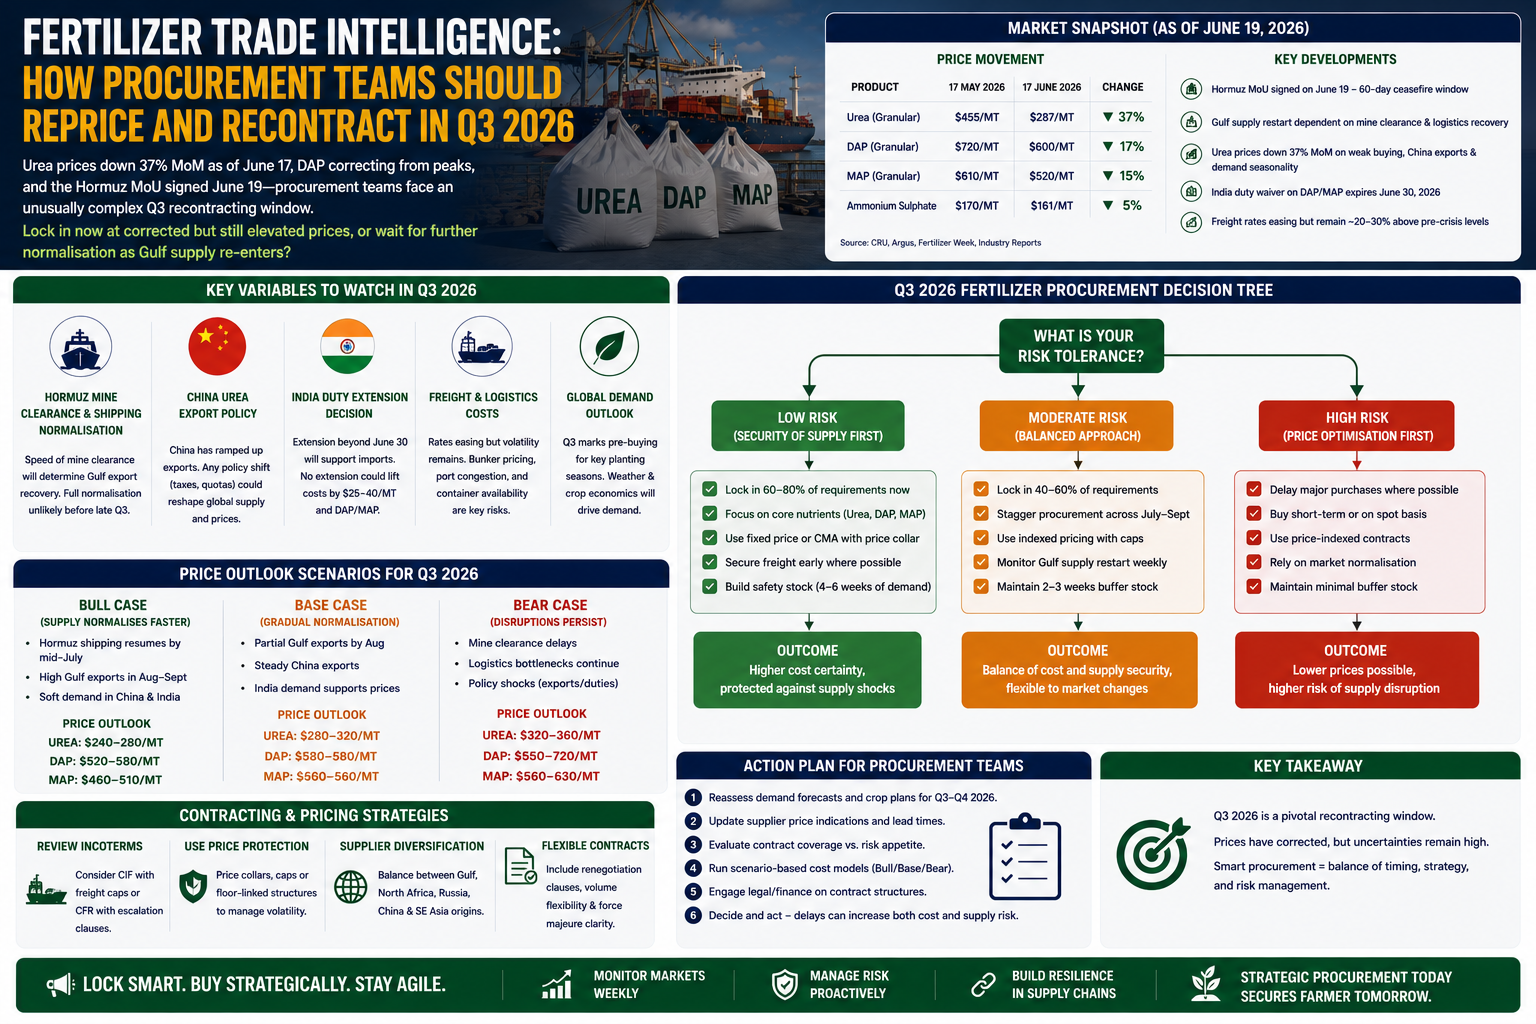
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.