Urea (Granular) - Egypt CAS: 57-13-6
The recent persistence of DAP price strength underscores a tightening phosphate supply chain, heightened global fertilizer demand, and growing procurement risks for agriculture stakeholders. As phosphate trade remains constrained, buyers must reassess sourcing strategies amid volatile market conditions.
China’s urea export limits and aggressive methanol-to-olefins (MTO) rates set the stage for 2026 chemical flows. July pricing decisions will reveal whether China will defend its crisis‑era share or recalibrate toward market balance. Global buyers must watch China’s export strategy closely.
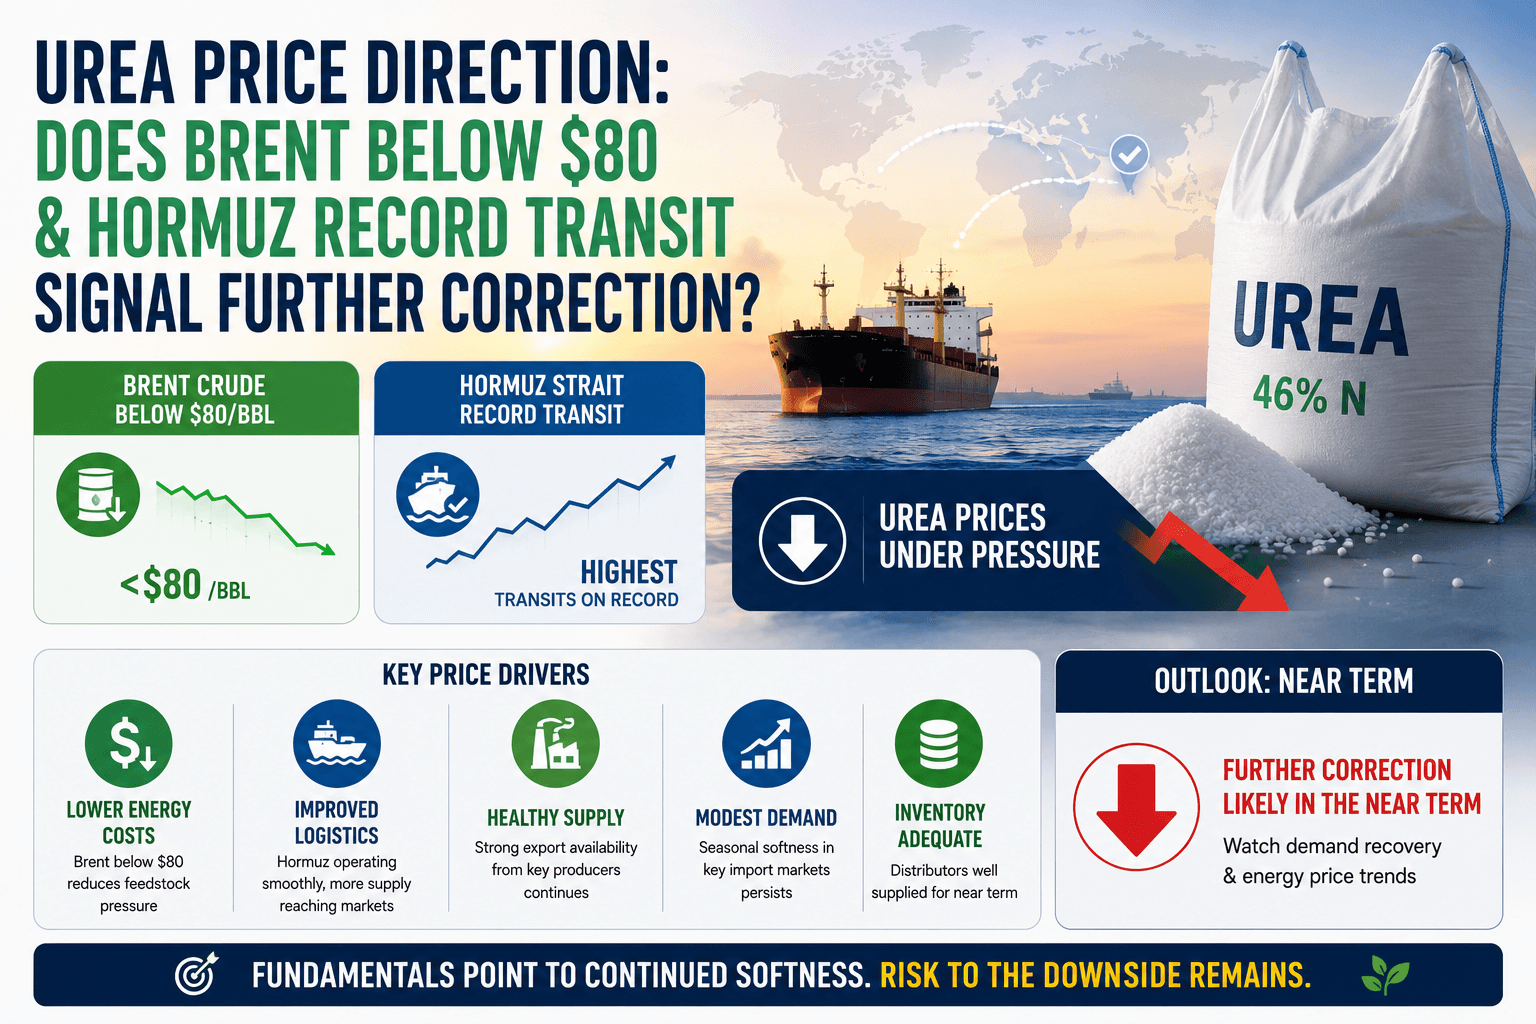
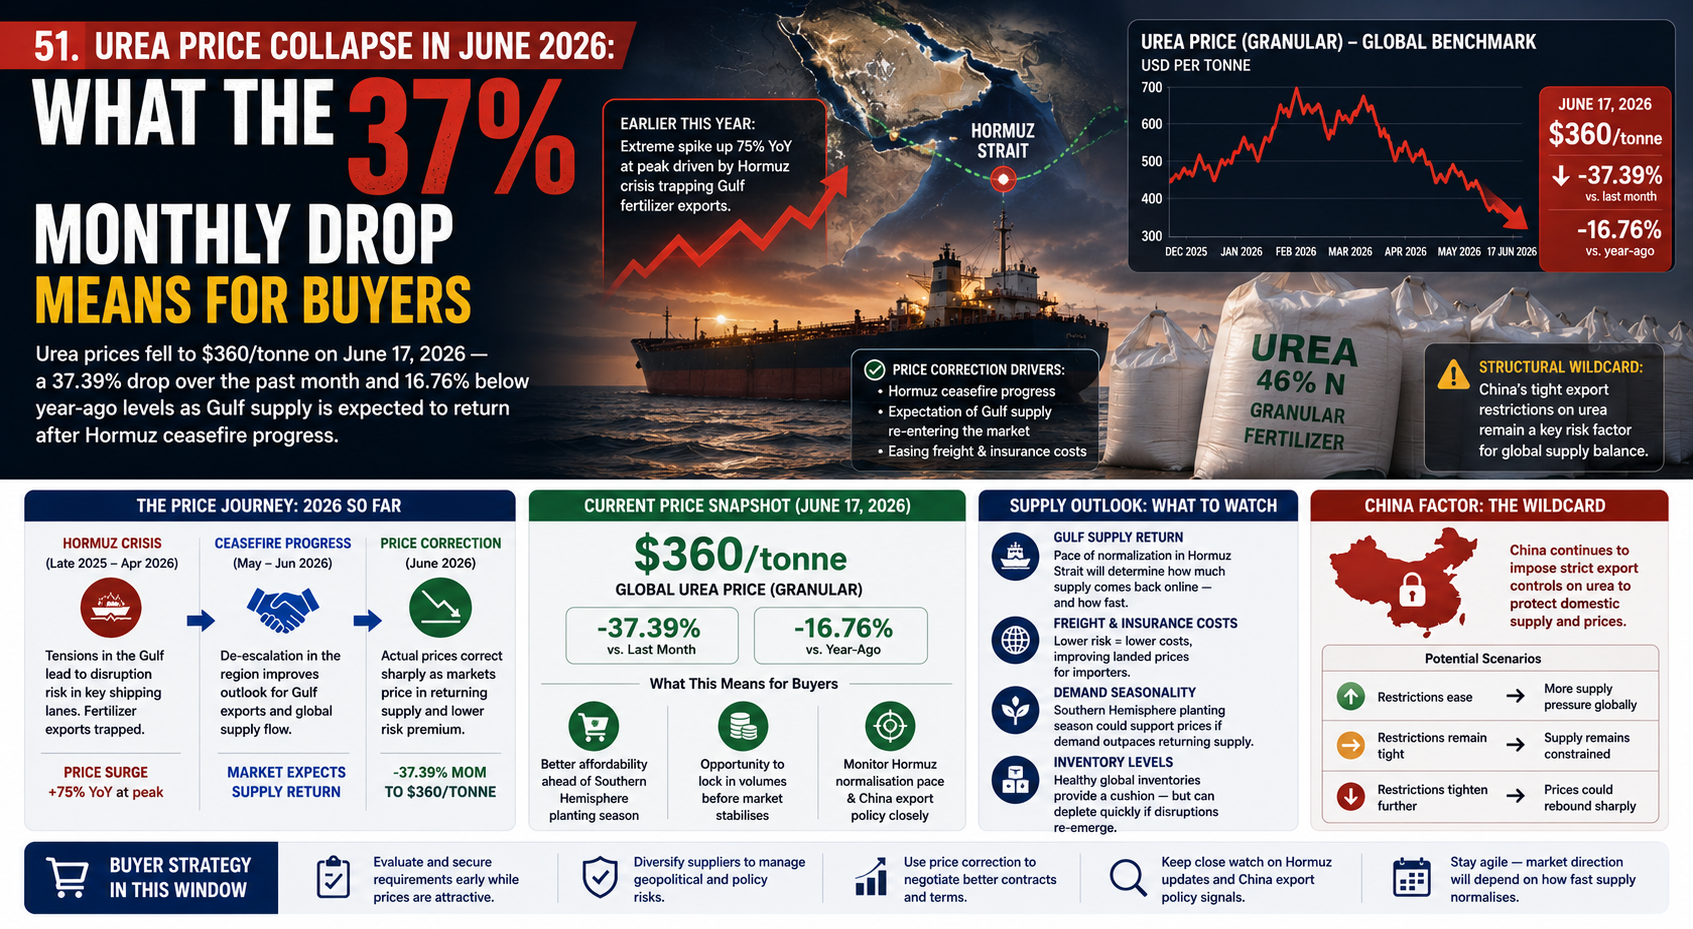
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.
The June 2026 fertilizer intelligence report covers the volatile first half, examines Gulf supply recovery, and projects urea and DAP outlooks for the second half. It highlights key price drivers, inventory trends, and policy impacts shaping the 2026 market.
Urea prices have dropped sharply after the Hormuz MOU, creating potential buying opportunities for fertilizer buyers despite ongoing supply recovery challenges.
Sulfur prices doubled from January to April 2026, driven by the collapse of Gulf refinery output
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.